Best Money Apps of 2026: Top Picks to Budget, Save, and Invest
Choosing the best money apps can do more for your finances than almost any single budgeting decision, because the right app automates the habits you would otherwise forget. In 2026, these tools do far more than track spending: they round up purchases into savings, auto-invest spare change, flag suspicious charges, and send real-time alerts when a bill jumps. This roundup breaks down the categories that matter and the standout features to look for before you install anything.
There is no single perfect app for everyone. The best choice depends on whether your priority is budgeting, saving, investing, or sending money to friends. Let’s match the tool to the job.
What Makes the Best Money Apps Worth Installing?
A great finance app earns its place on your home screen by saving you time and money. Before downloading, judge each option against a short checklist:
- Security: bank-level encryption, two-factor login, and read-only account connections.
- Automation: auto-transfers, round-ups, and scheduled bill reminders.
- Transparency: clear fees, no hidden subscriptions, and honest free tiers.
- Insight: useful categorization and reports, not just raw transaction lists.
The Federal Trade Commission reminds users that payment and banking apps are prime targets for scams, so strong security should always outrank flashy features.
The Main Categories of Finance Apps
Money apps fall into a few clear groups. Most people end up using two or three that cover different needs.
Budgeting and Expense Trackers
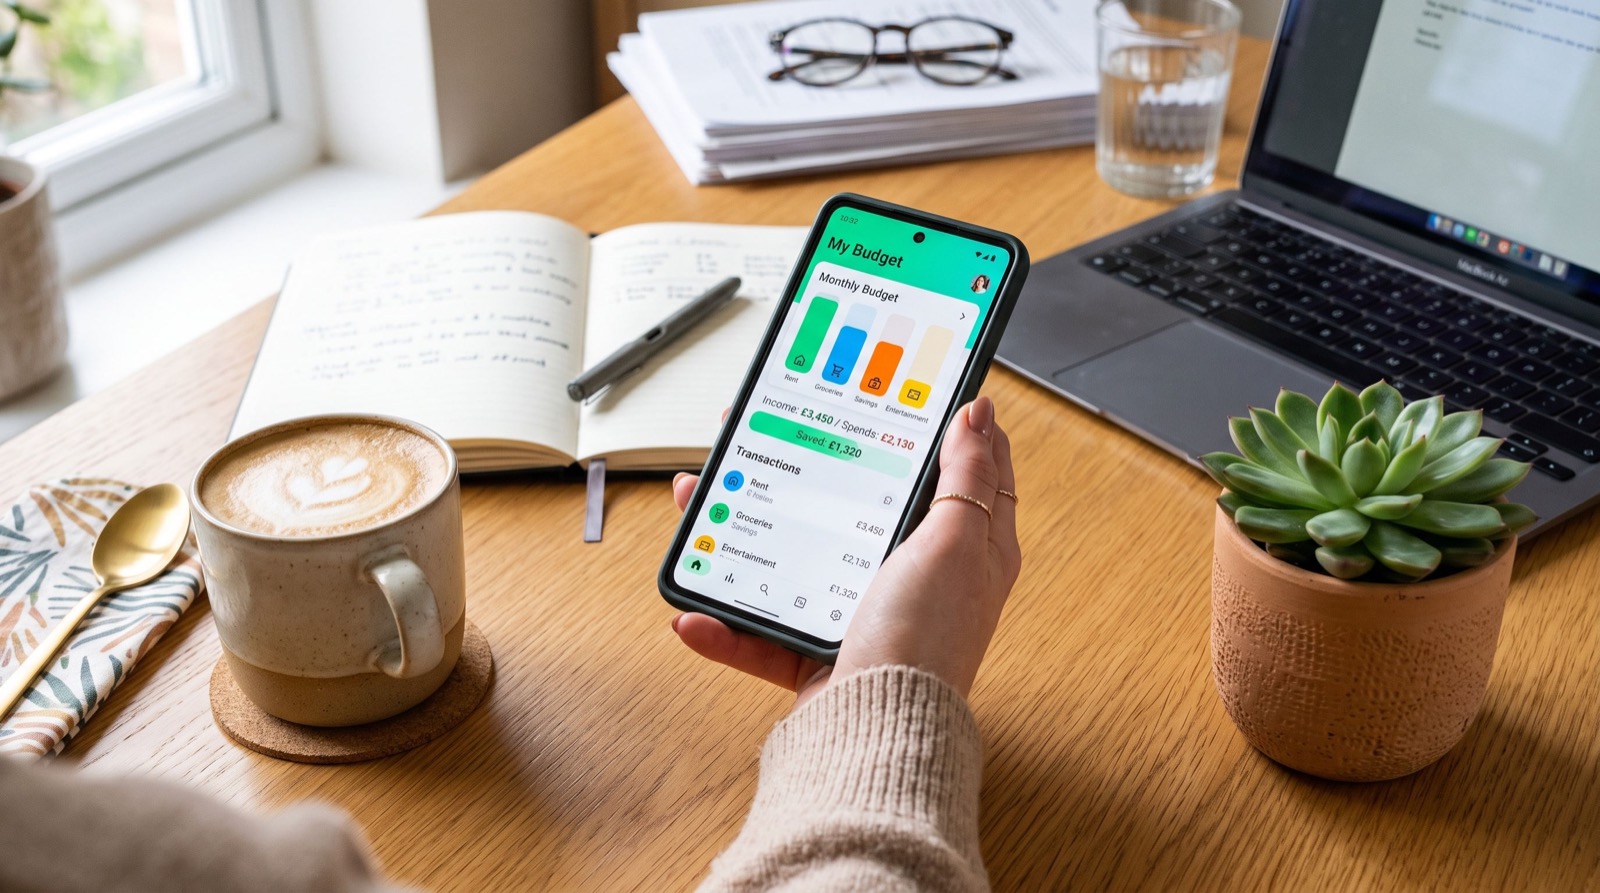
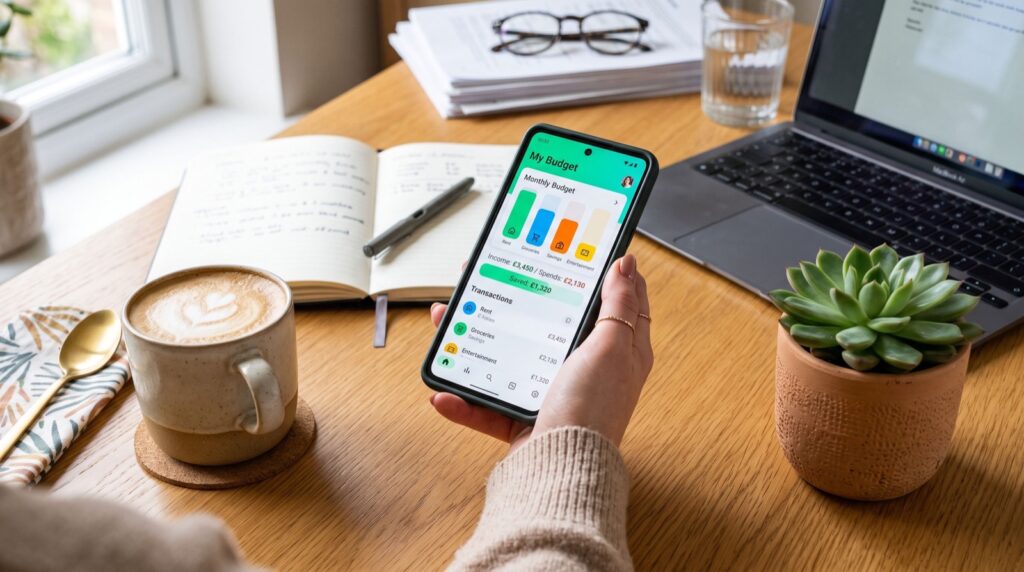
These apps connect to your accounts and sort every transaction so you can see where your money goes. The best ones let you set category limits and warn you before you overspend. They turn a monthly spreadsheet chore into a glance.
Saving and Round-Up Apps
Round-up apps quietly move spare change into savings every time you spend, which painlessly builds a buffer. Others automate goal-based saving, pulling a set amount toward a vacation or emergency fund on payday. Because the transfers are small and automatic, you barely notice them, yet they add up to hundreds of dollars over a year.
Micro-Investing and Robo-Advisor Apps
Investing used to require large minimums and a broker. Micro-investing apps changed that by letting you buy fractional shares with as little as a few dollars. Many pair this with a robo-advisor that builds a diversified portfolio based on your risk tolerance and rebalances it automatically. For first-time investors, these apps remove the two biggest barriers: intimidation and cost. Start small, enable automatic contributions, and let compounding work over years rather than weeks.
Peer-to-Peer Payment Apps
Sending money to friends, splitting a bill, or paying a freelancer is now instant. Payment apps have become everyday utilities, and if you want a thorough Cash App guide that explains fees, transfers, and safety features step by step, it is worth reading before you link a bank account.
Quick Comparison of App Types
The table below shows how the main categories compare on cost and ideal use so you can decide what belongs on your phone.
| App Type | Best For | Typical Cost | Key Feature |
|---|---|---|---|
| Budgeting tracker | Seeing where money goes | Free–$15/mo | Auto-categorization |
| Round-up saver | Painless saving | Free–$3/mo | Spare-change transfers |
| Micro-investing | Starting to invest | $0–$5/mo | Fractional shares |
| P2P payments | Sending cash fast | Free (fees for instant) | Instant transfers |
How to Combine Apps Without Overload
More apps is not better. Three well-chosen tools beat ten you ignore. A practical stack for 2026 looks like this:
- One budgeting app to track all spending in a single dashboard.
- One saving or investing app to automate wealth-building in the background.
- One payment app for everyday transfers and splitting costs.
Set each one up once, enable automation, and then mostly leave them alone. Check in weekly rather than obsessively, and let the automation carry your progress.
One practical tip from experience: use a single budgeting app as your financial “source of truth” and connect every account to it, including credit cards and savings. When all your money lives in one dashboard, you spot patterns quickly, catch double charges, and never wonder where a paycheck went. The other apps can specialize, but one should give you the full picture.
Avoid the common trap of app-hopping. Switching tools every few months resets your history and erases the trends that make budgeting useful. Pick solid options, commit for at least a year, and only switch if an app raises prices or loses a feature you rely on.
Keep Your Financial Documents Organized
Apps handle the day-to-day, but tax season still demands tidy records. Digitize receipts, statements, and contracts into a single secure folder so nothing goes missing. When you need to merge scans or combine statements into one file, lean on dependable specialists and tools that keep your paperwork clean and shareable with an accountant.
Where to Find Trustworthy Reviews
App-store rankings are easy to manipulate, so treat them with caution. Independent review hubs that test tools hands-on and disclose how they make money give a clearer picture. For a regularly updated shortlist of the best money apps across budgeting, saving, and investing, bookmark a dedicated finance resource and revisit it before you commit.
When comparing, read the fine print on fees, data sharing, and what happens to your information if the company is acquired. Your financial data is valuable, so guard it accordingly. The Consumer Financial Protection Bureau publishes free, unbiased guides that help you evaluate financial tools and understand your rights before you sign up.
Frequently Asked Questions
Which money app should a beginner start with?
Start with one free budgeting app that auto-categorizes spending. Once you can see where your money goes, add a round-up saver to build a buffer automatically. Keep it simple before layering on investing tools.
Are money apps safe to link to my bank?
Reputable apps use encryption and read-only connections that cannot move your money. Enable two-factor authentication, download only from official app stores, and never share your login credentials.
Do the best money apps cost money?
Many excellent apps offer free tiers that cover budgeting and basic saving. Paid plans add features like advanced reports or faster transfers, but most users can get strong value without paying.
Can one app do everything?
Some all-in-one platforms combine budgeting, saving, and investing, but specialized apps often perform each task better. A small stack of two or three focused tools usually works best.
The Bottom Line
The best money apps in 2026 turn good intentions into automatic action. Pick one budgeting tracker, one saving or investing tool, and one payment app, prioritize security over hype, and enable automation so progress happens in the background. Review your choices against the checklist above, read independent reviews before installing, and you will have a lean, powerful money toolkit working for you every single day.